
If a debtor has gone quiet, send a compliant Letter of Claim and keep a dated record of every contact attempt. The pre-action protocol normally gives the debtor 30 days to respond before you issue proceedings. If silence continues, seek judgment, then pick an enforcement route based on likely assets. For a company debtor, a statutory demand gives 21 days to pay.
TL;DR:
- Issuing early can trigger an adverse costs order; if the debtor replies, allow time for negotiation, commonly another 30 days.
- Request default judgment through Money Claim Online or form N225, but monitor the case because the defendant may still respond before the court processes it.
- Check assets before paying enforcement costs: wages, bank funds, goods, and property call for different remedies, and recovery is never guaranteed.
- A disputed company debt can derail an insolvency petition; confirm the debt is due and the demand was properly served before taking this public step.
Table of Contents
- What should you do first when your debtor stops responding?
- When can you start court proceedings after weeks of silence?
- How do you get judgment if the defendant never replies?
- Which enforcement route suits which debtor after a CCJ?
- Is a statutory demand the right tool against a company?
- What should you check before paying for enforcement?
- How can you re-engage a debtor who has stopped answering?
- What legal limits apply when you chase an unresponsive debtor?
- Could mediation or negotiation settle it faster than court?
- How do you keep an eye on a debtor’s finances?
- What does a debtor’s silence do to credit files and reputation?
- Why disciplined escalation beats aggressive tactics
- How we match your case to a vetted agency
- FAQ
- Sources
What should you do first when your debtor stops responding?
Silence is a stage in the process, not the end of it. The first job is to protect your position so every later option stays open. Your conduct may be relevant to the court, so build a clean paper trail from the first unanswered email.
- Log every attempt. Record dates, channels, copies of messages and delivery receipts, including read receipts and recorded-delivery slips.
- Send a Letter of Claim. It should follow the Pre-Action Protocol for Debt Claims and state the 30-day response expectation.
- Triage the case. Confirm the debtor’s identity, check Companies House for a limited company, look for obvious signs of assets, and note any vulnerability or regulated status that adds obligations.
- Keep the tone factual. Threats and sarcasm read badly in front of a judge, and a calm record supports any later costs argument.
- Avoid guessing at motives. Non-response often reflects confusion or fear rather than a clear refusal, as Brethertons’ analysis of the protocol suggests, so silence alone proves nothing about intent.
Pro Tip: Send every important letter by a trackable method and by email, and save the proof of delivery in the same folder as the letter itself.
When can you start court proceedings after weeks of silence?
The protocol sets the clock. From the date on your Letter of Claim, the debtor has 30 days to reply, and the protocol document itself explains how the Reply Form works. Issue too early and you risk an adverse costs order, because courts weigh pre-action compliance when they give directions, as the practice direction on pre-action conduct explains.
- No reply within the window: you can normally proceed to issue a claim.
- A reply arrives: the protocol expects you to allow further time for negotiation, commonly a further 30 days, before litigation is treated as reasonable.
- Genuine urgency: if you believe the usual timetable may not suit the circumstances, seek legal advice before proceeding.
- Evidence of compliance: note every unanswered chase, because the debtor’s silence is itself part of your record.
Our guide to UK debt collection timelines sets these windows out alongside the later enforcement deadlines.
How do you get judgment if the defendant never replies?
Once a claim is issued and the debtor files nothing in time, you can ask the court for judgment by default. The Money Claim Online user guide covers the online route. Paper claims use forms N225 or N225A instead.
- Check the deadline has passed. Confirm the defendant has filed neither a defence nor an admission within the time allowed.
- Choose the right judgment type. Request default judgment if there is no response, or judgment by acceptance if the debtor has admitted the debt.
- Submit through MCOL or the paper form. Attach any written admission to the request.
- Monitor the case. A defendant can still respond until the court processes your request, so check the case status daily.
- Move to enforcement. If the judgment stays unpaid, choose an enforcement route based on what the debtor owns or earns.
Which enforcement route suits which debtor after a CCJ?
Judgment is not payment. The GOV.UK EX321 guidance sets out the main remedies, and the right one depends on the debtor’s asset profile. Our overview of CCJ enforcement options goes deeper on each.
- Warrant of control: best where the debtor has premises or tangible goods. Enforcement agents seize and sell goods if payment is not made.
- Attachment of earnings: suits debtors on a salary, because the employer deducts payments. It does little for the unemployed or self-employed.
- Third-party debt order: freezes money in a bank account or sums owed to the debtor. Part 72 of the Civil Procedure Rules requires written evidence, and third parties can object. Our explainer on the third-party debt order walks through the application.
- Charging order: secures the judgment against property the debtor owns. Weigh the time it takes and how much equity the debtor actually has.
- Match method to assets: enforcement fees are added to the debt, but recovery is never guaranteed, so spend only where recoverable value justifies it.
For a warrant of control, GOV.UK says the enforcement agency’s letter demands payment within 7 working days, and an agent may visit after 15 working days to seize goods. The warrant lasts a year and can be suspended and reissued, so you have a window to work within.
Is a statutory demand the right tool against a company?
For a limited company, a statutory demand is a formal lever with a clear clock. A statutory demand under the Insolvency Rules must give the company 21 days from service to pay or secure the debt before you can present a winding-up petition. The demand has to carry specific statements and be dated and authenticated, as the rules on statutory demands require.
- Be sure the debt is clearly due. A disputed debt invites an application to restrain your petition.
- Check service was proper. A petition built on a defective demand can fail at the first hearing.
- Remember petitions are public. A winding-up petition is a serious step, so ask whether it is proportionate to the sum owed.
- Attend the hearing. Under the insolvency practice direction, petitions where no one attends can be dismissed or re-listed, and you may need a witness statement explaining non-attendance.
What should you check before paying for enforcement?
Enforcement can involve costs, and recovery is not guaranteed if the debtor has no assets. A short checklist stops you throwing good money after bad. Our debt collection checklist offers a longer version for UK businesses.
- Search for assets. Check the Land Registry for property and Companies House for filings and charges, and trace bank accounts where you lawfully can.
- Estimate recoverable value. Compare likely recovery with the fees and time each route needs.
- Gather your evidence. Keep the Letter of Claim, delivery attempts, replies or silence, and any settlement offers together.
- Check for vulnerability. If the debtor may be vulnerable, use a short checklist and calm, non-threatening scripts, since a proportionate approach can produce a repayment plan where threats would not.
Pro Tip: Run the asset search before you issue the claim, not after judgment, so you can pick the enforcement route while the case is still moving.
How can you re-engage a debtor who has stopped answering?
People go quiet for ordinary reasons: embarrassment, a cash squeeze, or a pile of unopened post. A structured approach often gets a reply where pressure does not. Change the channel before you change the tone. If emails vanish, try a short text, a phone call at a different time of day, or a letter to the registered office. Creditors may rely on only one route.
Keep each message short and specific. State the amount, the invoice reference, the due date and one clear action, such as “reply with a payment date”. A precise request makes it clear what response you are seeking.
Offer a way out that protects your position. A staged repayment plan, confirmed in writing, may offer a practical route to resolving a dispute. Set the terms clearly: instalment amounts, dates, and what happens if one is missed. If you agree terms verbally, send a written summary promptly.
Stay consistent. Firm, predictable follow-up can help keep the process moving. Fix a rhythm, perhaps a reminder, a call, then the formal Letter of Claim, and stick to it. Always keep copies, because every contact attempt, answered or not, adds to the record you will rely on if the case reaches a judge.
What legal limits apply when you chase an unresponsive debtor?
Chasing a debt does not suspend the rules on how you behave. Keep contact reasonable, factual and proportionate, and seek legal advice if you are unsure what is appropriate.
The pre-action protocol is the main procedural limit. Skip it and a court can penalise you on costs even if you win the underlying claim. Courts also expect you to treat the debtor’s rights seriously: if a debtor replies with a dispute, you generally need to engage with it and allow time rather than ploughing on.
Limitation matters too. Check the applicable time limit for your claim before committing to costs. If you are close to a deadline, take legal advice promptly.
Data handling is another boundary. Handle debtor information carefully and seek advice on the data protection requirements that apply to your situation. If the debtor is a consumer, extra care applies, particularly where the debtor is vulnerable or where regulated credit is involved. Our guide to legal debt recovery covers how these obligations interact with enforcement. None of this replaces advice on your own case, so consult a solicitor where the sum is large or the facts are contested.
Could mediation or negotiation settle it faster than court?
Sometimes. Alternative dispute resolution fits best when the debtor does not deny the debt but disputes the amount, the timing or the quality of what you supplied. The protocol itself expects parties to try to resolve matters before litigation, so a documented attempt at settlement helps you either way.
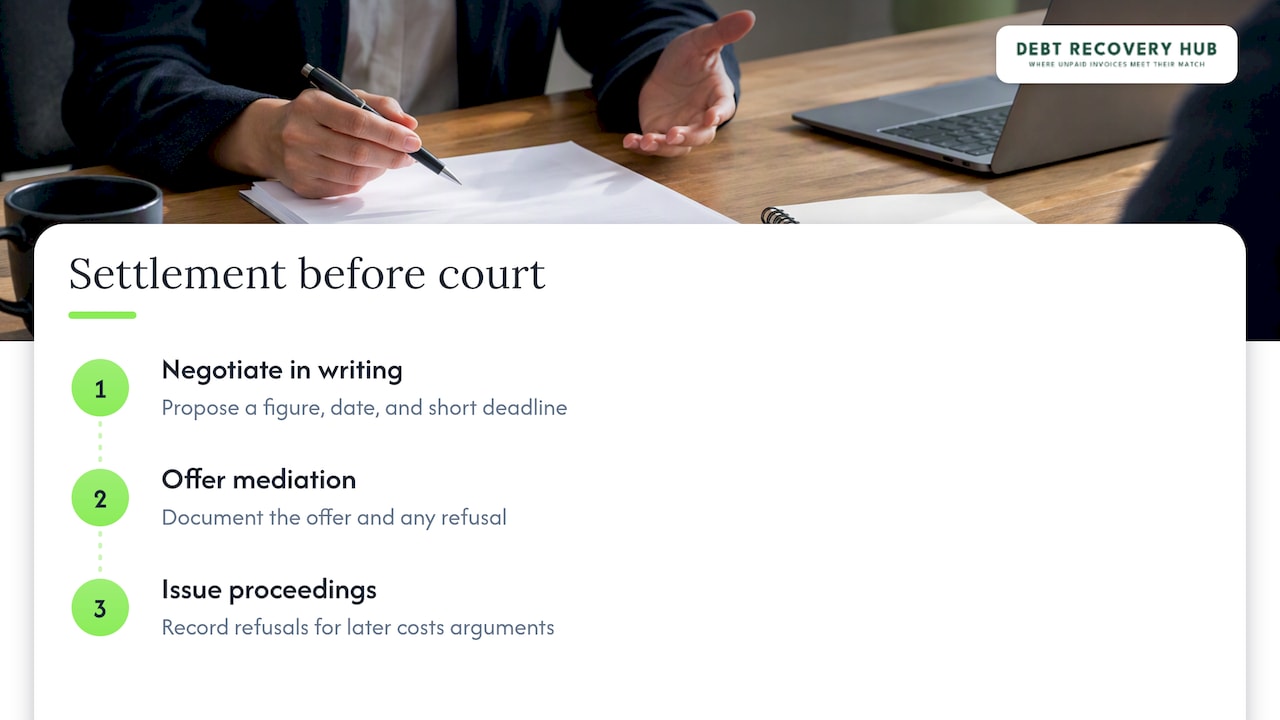
Negotiation is the simplest form. Propose a figure and a date, put it in writing, and set a short deadline for acceptance. A modest discount for fast payment can beat months of court time, particularly for smaller sums where enforcement costs eat the recovery.
Mediation brings in a neutral third party, who helps both sides find terms. It is confidential, usually quicker than a trial, and keeps the commercial relationship alive if you want to keep trading. It works poorly where the debtor refuses to engage at all, because both sides must turn up.
A sensible sequence is to negotiate first, then offer mediation, then issue proceedings if both fail. Keep every offer in writing and mark settlement proposals appropriately, so you know what you can later show a court. Document refusals as carefully as agreements. If a debtor ignores an offer of mediation, keep a record of the offer and consider taking advice on its relevance to any later costs argument.
How do you keep an eye on a debtor’s finances?
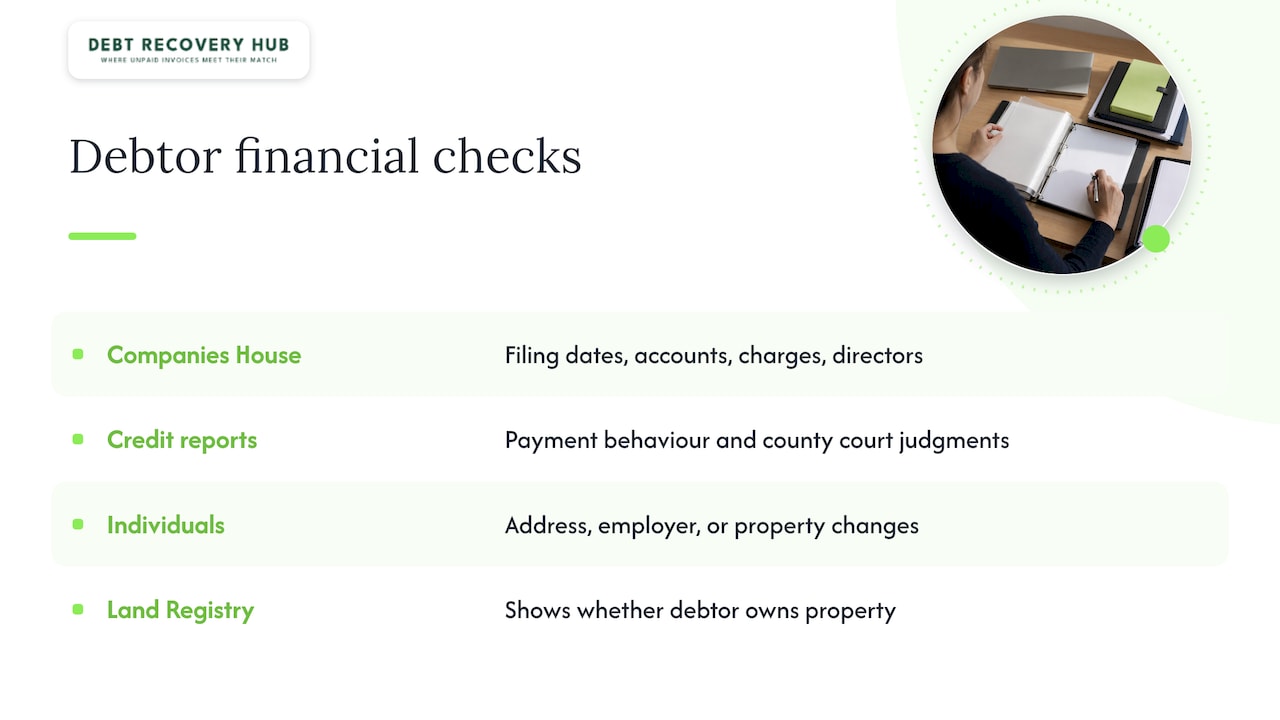
Monitoring turns a guess into a plan. For limited companies, you can check Companies House for filing dates, accounts, charges, director changes and insolvency notices. Late or missing accounts can signal trouble, though they are not proof of it.
Credit reference reports may provide information about payment behaviour and county court judgments. Treat them as signals, not verdicts, in line with the academic argument that non-response alone should not justify adverse inferences about risk. Verify before you act on any single indicator.
For individuals, look for visible changes: a new address, a change of employer, a property sale. Land Registry searches show whether the debtor owns property that a charging order could secure.
Build monitoring into a routine rather than a one-off check. Diarise a review for each material debtor, say before you issue a claim and again before you choose enforcement, because assets move. A debtor with nothing in January may have a salary, a vehicle or a bank balance by spring.
Record what you find and when. Dated notes of your checks show a court you acted reasonably, and they tell you which enforcement route has the best chance. If a debtor looks close to insolvency, speed matters, so consider whether a statutory demand or an early application is warranted.
What does a debtor’s silence do to credit files and reputation?
Silence by itself does not establish what may appear on a credit file. A county court judgment may be relevant to credit records. That is useful leverage: many debtors respond quickly once they realise a judgment could follow them into future borrowing.
For your own business, letting late payments go unaddressed may create reputational risks. A consistent, documented collections process protects your cash flow and your standing with suppliers and lenders who read your accounts.
Be careful about what you say publicly about a debtor, and seek legal advice before sharing information with third parties. Keep the dispute between the parties and the court.
Our guide to recovering unpaid invoices explains how earlier, firmer credit control reduces how often you reach this stage. Internal discipline helps too. This invoice collection plan from a field service software provider sets out a process and indicators for small firms to chase invoices before litigation becomes necessary.
If a debtor’s silence continues, remember that a judgment may have consequences for them, but it is not a substitute for considering the risks and costs of enforcement.
Why disciplined escalation beats aggressive tactics
In my view, the businesses that recover the most are rarely the loudest. Silence often masks complexity, such as a cash gap, a dispute the debtor has not voiced, or sheer avoidance, rather than malice. A measured, documented escalation keeps every option alive and keeps you credible with the court.
Angry messages feel satisfying and cost you later. Asset checks and the right enforcement route do the real work. For many businesses, a vetted match to an agency also saves the early mistakes of choosing blind.
— Jack
How we match your case to a vetted agency

If you would rather hand the chasing to a specialist, we match your case to a vetted debt collection agency based on the debt type, amount, age and location, so you are not choosing blind. Start with our business debt recovery page. Before you ask for a match, gather:
- The debt amount and how old it is
- Your Letter of Claim and any court documents
- Your communication log
- Any basic asset checks you have run
A well-prepared case saves time on choosing the right enforcement route and avoids unsuitable, costly methods. Send us your details today to check which agencies fit your case.
FAQ
What happens if the debtor ignores a Letter of Claim?
Once the 30-day response period under the pre-action protocol has passed, you can normally issue a court claim. Keep your proof of delivery and your log of chasers, because a court can treat the silence as unreasonable conduct when it considers costs.
What can you do if a debtor cannot pay a judgment?
Choose enforcement according to what the debtor has, such as goods, wages, bank funds or property. GOV.UK guidance notes that enforcement fees are added to the debt but recovery is not guaranteed if no assets exist, so run asset checks first.
Can you get judgment if the defendant never responds to the claim?
Yes. If no defence or admission is filed in time, you can request default judgment through Money Claim Online or on form N225. Monitor the case, because a defendant can still reply until the court processes your request.
How long does a company have to respond to a statutory demand?
A company has 21 days from service to pay or secure the debt before you can present a winding-up petition, under the Insolvency Rules. Make sure the demand is correctly worded and authenticated.