
Recovering a debt from a European debtor is achievable, and the fastest route depends on whether the claim is contested. For uncontested invoices, a European order for payment or an account preservation order often moves faster than a full lawsuit; for disputed debts, you will usually need a court judgment and formal recognition abroad. Before spending on legal action, confirm the debtor’s exact jurisdiction, check limitation periods, and verify that any judgment you obtain will actually be enforceable where the debtor holds assets.
TL;DR:
- Gather the contract, invoices, delivery records, and payment correspondence, then verify the governing law, jurisdiction clause, debtor’s status, and limitation period before spending on recovery.
- For a straightforward unpaid invoice, send a documented demand allowing 14 to 21 days, then consider a local collector before costly litigation.
- For uncontested invoices, standard forms provide a European order for payment, and the debtor has 30 days to oppose before it becomes enforceable.
- Seek an EAPO before or during proceedings only when evidence shows funds may disappear; it can freeze bank accounts in another EU Member State.
- When the debtor contests the debt, expect court proceedings and potentially months of foreign enforcement; arrange certified translations and local counsel early.
Table of Contents
- Practical options: pre-claim action, negotiation and when to escalate
- Legal routes and recognition: EAPO, European order for payment and enforcement
- Step-by-step checklist for a recovery case against a European debtor
- Costs, interest and timelines for cross-border enforcement
- Choosing a local partner or a matching route
- Legal differences among key European jurisdictions affecting debt recovery
- The impact of GDPR and data protection law on debt collection
- The role of mediation and alternative dispute resolution
- Why careful intake changes recovery outcomes
- How Debtrecoveryhub helps you find the right recovery partner
- FAQ
- Sources
Practical options: pre-claim action, negotiation and when to escalate
The moment an invoice goes unpaid, start a paper trail. Pull together the contract, purchase order, delivery confirmation and every email exchange about payment terms, because these documents decide whether later legal steps succeed.
A firm but professional demand letter is usually the next move. It should restate the amount owed, reference the contract clause that was breached and set a clear deadline, typically 14 to 21 days, before escalation follows. Many disputes resolve at this stage once the debtor realises you are organised and prepared to act.
When a letter goes unanswered, you have two broad paths: instruct a local collector who knows the debtor’s market and language, or bring in a lawyer qualified in the debtor’s jurisdiction. A local collector tends to be faster and cheaper for straightforward commercial debts; a lawyer becomes necessary once the debt is disputed or court action looks likely.
- Document everything from day one: contracts, invoices, delivery proof and correspondence.
- Send a written demand with a firm deadline and named consequences for non-payment.
- Check whether the debtor’s assets are at risk of being moved or dissipated before you escalate.
- Match the escalation route to debt size: smaller sums rarely justify full litigation costs.
Escalate to a formal legal procedure when the debtor disputes the claim outright, stops responding entirely, or shows signs of insolvency. Asset preservation measures sit early in this decision tree: if you suspect funds might disappear, applying for a freezing order before filing the main claim can protect your position.
Pro Tip: Request a debtor’s registered company details and recent filing history before you commit to legal fees, since an insolvent or dissolved entity changes the entire strategy.
Legal routes and recognition: EAPO, European order for payment and enforcement
Three mechanisms cover most cross-border scenarios, each suited to a different stage of the dispute.
The European Account Preservation Order lets a court in one EU Member State freeze a debtor’s bank funds held in another Member State, provided the creditor demonstrates a genuine risk that the money will be moved or spent before judgment. It can be requested before or during proceedings, which makes it a useful tool when you fear a debtor is about to empty an account, though it only reaches funds within EU Member States and carries its own procedural conditions.
For debts that are not seriously disputed, the European order for payment procedure offers a streamlined path. It uses standard forms across participating states and gives the debtor a defined window, commonly 30 days, to lodge an opposition; if none arrives, the order becomes directly enforceable. This route suits straightforward unpaid invoices where the facts are not in question.
Once you hold a judgment, recognition in the debtor’s country is the next hurdle. The Hague Convention 2019 implementing regulations bring a registration model into UK law for recognising and enforcing certain foreign judgments, meaning creditors typically register the judgment in the requested state and prepare for a possible set-aside application rather than expecting immediate enforcement. The government’s response to Hague 2019 sets out the practical steps involved in that registration process.
- EAPO: fast, pre-emptive, limited to freezing EU bank accounts under defined risk conditions.
- European order for payment: fastest route for uncontested pecuniary claims, with standard EU-wide forms.
- Hague 2019 registration: the main fallback once you hold a judgment that needs recognition abroad.
- National enforcement procedures: necessary when no multilateral instrument applies or the debtor’s assets sit outside the covered framework.
If none of these instruments apply to your case, you fall back on the debtor country’s own enforcement rules, which usually means instructing local counsel to pursue the claim through the national courts directly.
Step-by-step checklist for a recovery case against a European debtor
Work through these steps in order, since skipping one often costs time later.
- Confirm the contract’s governing law and jurisdiction clause before anything else.
- Gather invoices, signed delivery notes, purchase orders and all payment-related correspondence.
- Locate the debtor through company registry searches, trade directories and any bank details on file.
- Send a written demand letter with a specific payment deadline and stated consequences.
- Choose your route: a local collector for straightforward cases, an EAPO application if assets are at risk, or formal proceedings if the debt is contested.
- Prepare for enforcement by arranging certified translations, notarisation where required, and instructing local counsel who can estimate realistic recoverable sums.
Pro Tip: Translate key documents early, since a court or local agency asked to act on an uncertified or late translation will often return the request, adding weeks to the process.
Missing documentation is the single biggest reason recovery stalls once a case reaches a foreign court or collector, so treat this currency compliance checklist as the minimum, not the ideal.
Costs, interest and timelines for cross-border enforcement
Under Directive 2011/7/EU, standard B2B payment terms default to 60 days unless otherwise agreed, and creditors are entitled to statutory interest plus recovery costs once a payment is late. GOV.UK guidance sets fixed compensation bands for UK creditors: a fixed amount depending on the size of the debt, with increasing bands for small, medium, and large debts, alongside a right to claim additional reasonable recovery costs where they exceed the fixed sum.
- EAPO applications: typically the quickest tool once a genuine risk of asset dissipation is shown.
- European orders for payment: fast for uncontested claims, since no opposition means the order becomes enforceable without a trial.
- National enforcement proceedings: slower, often running months rather than weeks once a judgment needs registering and enforcing abroad.
- Additional costs to budget for: certified translations, local counsel fees and court or bailiff enforcement charges.
Choosing a local partner or a matching route
The right partner depends on the debtor’s location, the debt’s size and how contested the claim is. Look for proven enforcement experience in the debtor’s specific jurisdiction, genuine local-language capability, a transparent fee model, and solid evidence handling practices rather than a generic “international” label.
- Enforcement track record in the debtor’s own country matters more than a broad international presence.
- A clear fee structure, whether contingency or fixed, avoids disputes once funds are recovered.
- Local-language capability speeds up correspondence with debtors and local courts alike.
- Compliance with any applicable licensing or regulatory regime reduces the risk of an abusive-practice complaint.
A thorough intake, covering debtor identifiers, contract terms, invoice history and prior contact attempts, lets a matching service or law firm assess the case accurately and move straight to instruction rather than requesting the same information twice. This matters most for mid-value commercial debts where the cost of choosing the wrong provider can exceed the debt itself.
Legal differences among key European jurisdictions affecting debt recovery
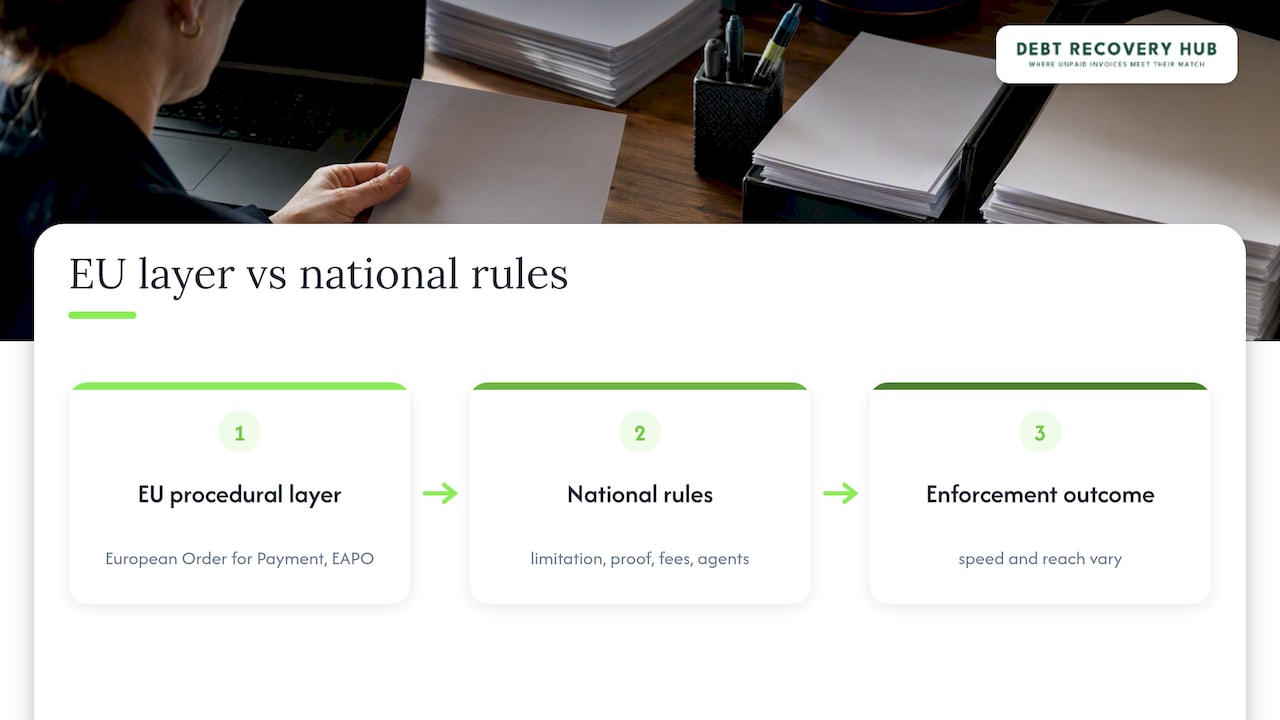
European debt recovery is not a single system; it is a patchwork of national procedures layered under EU-wide instruments. Limitation periods vary significantly by country, as do the documentary standards courts expect for a valid claim, and what counts as sufficient proof of debt in one jurisdiction may fall short in another.
Enforcement mechanics differ too. Some countries rely heavily on court bailiffs to seize assets, others use dedicated enforcement agents with wider powers, and the speed of each process depends on local court backlogs as much as the law itself. Scholarly analysis of EU member states’ collection practices points to fragmented regulatory regimes across the bloc, with sector-specific licensing for collectors absent in many member states and enforcement practices varying accordingly.
This fragmentation is precisely why EU-wide instruments like the European order for payment and the EAPO exist: they create a common procedural layer that sits above these national differences for the categories of claim they cover. But once you move outside those instruments, for example to seize physical assets or pursue a debtor’s property, you are back in the debtor country’s own civil procedure, with its own court fees, document requirements and timelines. A claim that moves quickly in one jurisdiction can stall in another purely because of how that country’s enforcement agents are structured, which is why confirming the debtor’s exact location before committing to a strategy is not a formality but a genuine determinant of outcome.
The impact of GDPR and data protection law on debt collection
Chasing a debtor abroad means handling personal data, names, addresses, contact details and financial records, across borders, and the General Data Protection Regulation governs how that data moves and is used throughout the EU. Any transfer of personal data from an EU-based system to a UK-based collector, or the reverse, needs a lawful basis and appropriate safeguards, which in practice means contracts, data processing agreements or recognised transfer mechanisms between the parties involved.
Debt collection itself is a recognised legitimate activity under data protection law, but that does not remove the obligations around proportionate data use. Collectors should hold only the data needed for the specific case, keep it secure, and avoid sharing debtor details with parties who have no legitimate role in the recovery.
This has a direct practical effect on cross-border cases: a local agency or lawyer in the debtor’s country will often ask for a clear basis for processing the debtor’s data before they begin work, and vague or incomplete instructions can slow down onboarding. Supplying a tight, well-documented case file, with the data processing basis already considered, helps a receiving agency start work immediately rather than pausing to request compliance confirmations. Given the fragmented regulatory landscape already noted across member states, data protection compliance is one more area where local expertise reduces risk rather than adding friction.
The role of mediation and alternative dispute resolution
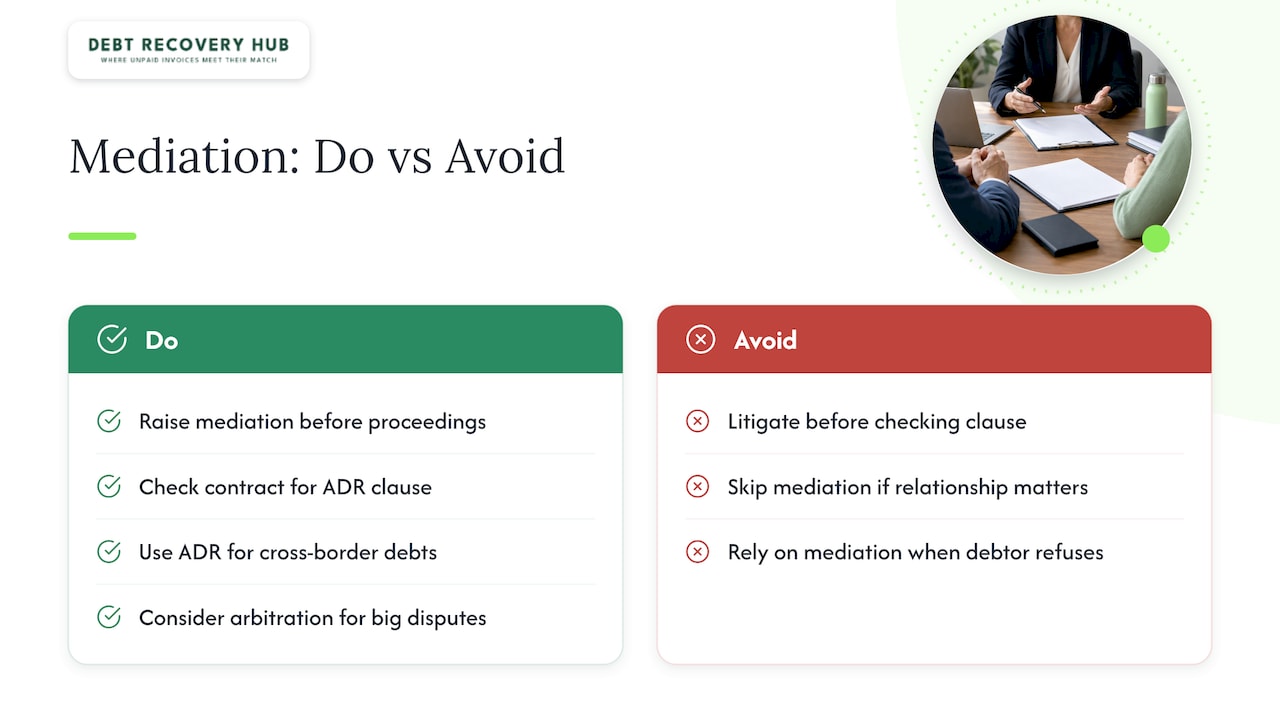
Court proceedings and formal enforcement are not always the first or best option, particularly where the commercial relationship is worth preserving or the amount in dispute does not justify litigation costs. Mediation offers a structured, confidential process where both parties negotiate toward a settlement with a neutral third party facilitating discussion, rather than a court imposing an outcome.
For cross-border commercial debts, mediation can be faster and considerably cheaper than pursuing recognition and enforcement through multiple jurisdictions, especially when the debtor disputes only part of the invoice or has a genuine cash-flow issue rather than an intent to avoid payment. Many commercial contracts now include a mediation or arbitration clause requiring the parties to attempt resolution before litigation, and checking for that clause early avoids wasted legal spend on a route the contract itself has already closed off.
Alternative dispute resolution more broadly, including arbitration for larger commercial disputes, gives creditors a way to obtain a binding outcome without relying solely on national court systems and their varying timelines. It will not suit every case: a debtor who is simply unwilling to engage has little incentive to participate in mediation, and in those situations the formal legal routes outlined earlier become necessary. But for disputed or partially disputed debts where some relationship or ongoing trade is at stake, raising mediation before issuing proceedings is worth the modest extra time it takes.
Why careful intake changes recovery outcomes
Most wasted legal spend traces back to a case that was never properly prepared, not to the law itself. A structured intake that captures debtor identifiers, contract terms and evidence upfront lets a vetted local agency assess the case accurately and move straight to action instead of circling back for missing documents. Where asset preservation is realistic, acting within days, not weeks, often determines whether funds are still there to recover.
— Jack
How Debtrecoveryhub helps you find the right recovery partner

Our matching process is designed around the principle that a recovery case moves quickly when the right local partner has the full picture from day one. When you submit your case, we collect the debt type, amount, age and the debtor’s location, then match you with agencies suited to that specific profile rather than leaving you to contact providers at random.
This matters most for cross-border cases, where the wrong agency choice can waste weeks before anyone touches the real work. Our International Debt Recovery service covers exactly this situation, connecting you with partners experienced in the debtor’s jurisdiction so your case starts with someone who already understands the local procedure. Submit your case details to get matched with a vetted agency suited to your claim.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
FAQ
Can a foreign debt be collected in the UK?
Yes, a foreign debt can be pursued against a debtor based in the UK, typically once the creditor holds an enforceable judgment or order that qualifies for recognition under the relevant framework. The specific route depends on where the original judgment was issued and whether a recognised instrument, such as the Hague 2019 arrangements, covers that country.
What happens if a European debtor disputes the claim?
A disputed claim usually moves out of the fast-track procedures, such as the European order for payment, and into standard court proceedings in the debtor’s jurisdiction. This typically means longer timelines and higher costs, since the dispute must be argued and decided before any enforcement can begin.
How does an EAPO protect a creditor during a dispute?
An EAPO freezes a debtor’s bank funds in another EU Member State where a genuine risk of asset dissipation exists, preserving money that might otherwise disappear before judgment. It can be requested before or during the main proceedings, giving creditors a protective step while the underlying claim is still being resolved.
What can creditors claim alongside the unpaid debt?
Creditors can typically claim statutory interest on the late payment plus a fixed recovery charge, which under UK guidance ranges from £40 to £100 depending on the debt’s size. Reasonable additional recovery costs, such as legal fees, may also be claimed where they exceed the fixed amount.
How long does cross-border debt recovery usually take?
Timelines vary widely depending on the route: an EAPO or an uncontested European order for payment can move in weeks, while a disputed claim needing full court proceedings and foreign enforcement can take many months. The debtor’s cooperation, the jurisdiction involved and whether assets are easily located all affect the final timeline.
Sources
- European Account Preservation Order (EAPO) — summary
- The Recognition and Enforcement of Judgments (2019 Hague Convention etc.) Regulations 2024