
Recovering a debt from the UAE is often possible, but the outcome depends on your paperwork, the forum you choose and whether the debtor still holds recoverable assets. Start now by gathering your contract, invoices and any written acknowledgement of the debt, then send a formal demand letter or speak to a UAE-qualified adviser. Act early, because a UAE judgment does not automatically enforce in the UK, so your enforcement strategy needs planning from day one.
TL;DR:
- Use a payment order for a clearly documented, undisputed debt; disputes over amounts or terms require ordinary proceedings, while arbitration depends on a contract clause.
- Prepare signed contracts, invoices, delivery records, and written admissions, then arrange certified Arabic translations and preserve complete message threads with timestamps.
- Trace assets before committing to litigation: UAE courts can order precautionary attachment or travel bans before judgment when evidence shows a real risk of evasion.
- A UAE judgment does not automatically enforce in the UK; pursue a fresh claim or recognition only if the debtor has traceable UK assets.
- For federal entities, creditors must notify debtors within 10 business days after a missed payment deadline, creating a dated record for later proceedings.
Table of Contents
- A staged roadmap for recovering debt in the UAE
- Legal routes explained: payment orders, ordinary court claims and arbitration
- Choosing the right forum: onshore courts versus DIFC/ADGM or arbitration
- Enforcement and remedies: turning judgments into payment
- What to prepare now: evidence, documents and steps before formal action
- Recovering a UAE debt from abroad: enforcement in the UK and cross-border options
- Timelines, limitation periods and practical timing
- How we think about UAE debt recovery
- How we can help: recovering your UAE debt through DebtRecoveryHub
- FAQ
- Sources
A staged roadmap for recovering debt in the UAE
Debt recovery in the UAE generally follows a predictable sequence, and skipping a stage can weaken your position later. Each step builds the paper trail that courts and enforcement officers expect to see before they act.
- Amicable contact: reach out directly, document every response, and escalate once a reasonable deadline passes without payment.
- Formal demand or notarised legal notice: this creates a dated, provable record that you demanded payment, which matters for later procedural steps. For federal entities, creditors must notify debtors within 10 business days of a missed due date.
- Payment order, ordinary claim or arbitration: well-documented, undisputed debts can move through an expedited payment order, while disputed or complex claims need a full court or arbitral hearing.
- Enforcement: once you hold a payment order, judgment or arbitral award, you apply to turn it into actual payment through seizure, attachment or other execution measures.
Bounced cheques and signs of insolvency change this sequence. A dishonoured cheque can support a faster claim route, while insolvency triggers bankruptcy procedures that affect your priority against other creditors and impose their own statutory timeframes.
Legal routes explained: payment orders, ordinary court claims and arbitration
Choosing the right procedure saves months. A payment order suits clear, undisputed debts backed by solid paperwork, and payment orders are effective for well-documented claims and can sharply reduce the time to an enforceable order. An ordinary civil or commercial claim becomes unavoidable once the debtor disputes the amount, the contract terms or the facts, since a judge then needs to hear evidence from both sides.
Arbitration suits parties whose contract already contains an arbitration clause, particularly in cross-border commercial deals, and an arbitral award generally travels better internationally than a court judgment once it is properly seized and recognised.
For documentary thresholds, keep these ready:
- Signed contract or purchase order showing the agreed amount and payment terms.
- Invoices, delivery notes or proof of service matching the contract.
- Any written acknowledgement of the debt, including emails or messages.
- A notarised demand letter showing you gave the debtor fair notice.
Pro Tip: Build enforcement-ready paperwork at the contract stage itself, with clear jurisdiction clauses and payment schedules, since well-drafted terms and documented acknowledgements improve recovery prospects and can open expedited routes such as payment orders.
Choosing the right forum: onshore courts versus DIFC/ADGM or arbitration
Forum choice shapes both the speed of your case and what happens once you win. Onshore courts operate mainly in Arabic under federal procedure, while DIFC and ADGM run proceedings in English with common-law style rules, which suits international contracts and parties unfamiliar with Arabic litigation.
- Onshore courts matter most when the debtor’s assets, such as property or a local bank account, sit within mainland UAE jurisdiction.
- DIFC or ADGM often suits contracts already referencing English law or international parties who prefer common-law procedure.
- Arbitration works well when your contract already names an arbitral seat and institution.
- The forum you choose also affects how easily a later judgment or award gets recognised abroad, since courts and tribunals differ in how their decisions travel across borders.
Picking the wrong forum can add delay and cost, since switching routes midway often means starting much of the groundwork again.
Enforcement and remedies: turning judgments into payment
A judgment or payment order is only useful once you can execute it. UAE legislation allows precautionary attachments and travel bans as interim measures where there is a real risk the debtor will move or hide assets, and these can sometimes be sought before a final judgment.
Once you hold an enforceable order, execution tools include:
- Freezing bank accounts to stop funds disappearing before you collect.
- Seizing and selling movable or immovable assets, from vehicles to property.
- Garnishing receivables owed to the debtor by third parties.
- Applying a travel ban where the debtor shows signs of evasion.
Insolvency changes the picture sharply, since the Bankruptcy Court must decide insolvency applications within short statutory timeframes, and creditors then compete for priority rather than enforcing individually. Practitioners generally find that asset discovery, not the judgment itself, is the real bottleneck, so bank enquiries, land registry checks and company filings often decide whether enforcement actually pays out.
Pro Tip: File for a provisional attachment as early as the facts allow. A final judgment against a debtor with no traceable assets recovers nothing.
Where a debtor has already slipped into formal insolvency, our liquidation procedures guide from Viau explains how UAE winding-up rules affect creditors who find themselves competing for a share of what remains.
What to prepare now: evidence, documents and steps before formal action
Strong preparation shortens every stage that follows. Gather this before you send a single letter.
- Collect the signed contract, all invoices, delivery notes and any correspondence referencing the debt.
- Save written admissions of the debt, including settlement negotiation emails or messages where the debtor acknowledges owing money.
- Arrange notarisation and certified translation of key documents, since UAE courts generally require Arabic versions of foreign-language evidence.
- Preserve digital evidence properly, including timestamps and full message threads rather than screenshots alone.
- Commission a solvency check or asset trace before committing to litigation, so you know whether a judgment will actually be worth pursuing.
Our guide to debt recovery letters sets out exactly what a formal demand should include to carry weight later in court.
Recovering a UAE debt from abroad: enforcement in the UK and cross-border options
There is no automatic reciprocal enforcement of UAE civil or commercial judgments in the UK. You generally need to bring a fresh UK action on the underlying debt or seek recognition under common-law principles rather than simply registering the UAE judgment.
UK enforcement makes sense when the debtor has traceable assets or connections in the UK. UK authorities confirm that foreign debt recovery works best when the debtor owns UK land or property, is employed by a UK-established business, or otherwise holds enforceable UK assets, and recovery becomes impractical without that link.
- Bring a fresh UK claim on the underlying debt when the UAE route offers little practical traction.
- Seek recognition or registration of a foreign award where a relevant treaty or common-law route permits it.
- Prefer UAE enforcement outright when the debtor’s assets, property or business sit inside the UAE.
- Serve documents carefully and keep certified translations, since procedural errors at this stage can delay a UK claim for months.
Our guide to enforcing a foreign judgment in the UK walks through which of these routes applies to your case, and our international debt recovery guidance covers the practical side of acting across two jurisdictions at once.
Timelines, limitation periods and practical timing
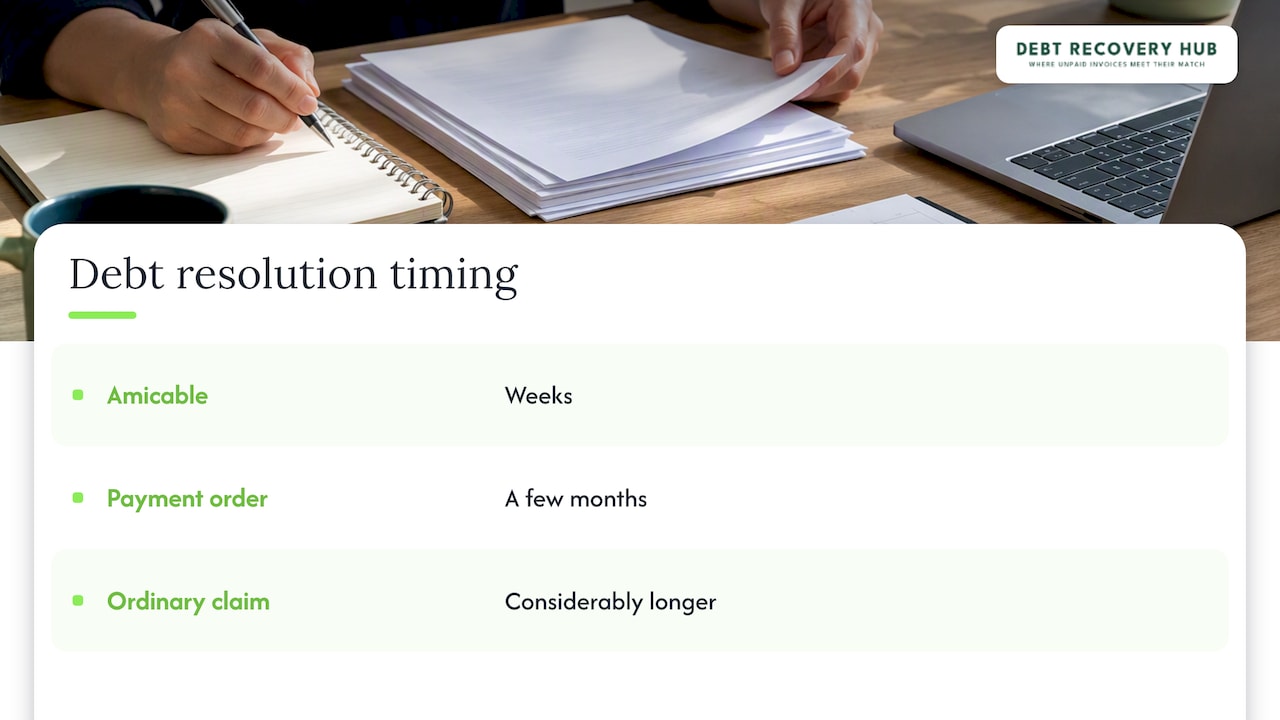
Amicable resolution can take weeks, a payment order often resolves in a few months when paperwork is clean, and full litigation through ordinary claims can run considerably longer. The date the debt arose matters enormously, since limitation periods run from that point and a late start can close off remedies entirely.
Cases up to AED 500,000 are often handled by the UAE Court of First Instance, which tends to move faster than higher-value claims routed through more senior courts.
Early precautionary measures, such as attachments sought before judgment, preserve your enforcement prospects far better than waiting for a final ruling. Where a debtor shows signs of insolvency, acting before a formal bankruptcy filing closes keeps you among creditors with a stronger claim rather than one competing late in a crowded queue.
How we think about UAE debt recovery
Most creditors lose ground by treating every UAE debt the same way, when in practice an undisputed invoice and a disputed commercial contract need entirely different agencies and entirely different procedural instincts. Matching a case to a UAE-capable agency that already knows the right forum and documentary threshold, rather than picking one at random, tends to produce faster and more defensible outcomes, particularly where cross-border enforcement is in play.
— Jack
How we can help: recovering your UAE debt through DebtRecoveryHub
We connect you with debt collection agencies based on the debt type, amount, age and the location of the debtor and their assets.

We collect relevant documents such as contracts, invoices and correspondence, then recommend agencies suited to your case, whether involving payment orders, litigation, or cross-border enforcement. For business debts owed from the UAE, start with our Business Debt Recovery service, or explore our Legal Debt Recovery page if your case has already moved into dispute.
Tell us about your case and we can help identify an appropriate debt recovery option.
This article is general information, not a substitute for advice from a qualified lawyer. Consult a qualified legal professional about your own circumstances before acting on anything here.
FAQ
Can UAE debt be enforced in the UK?
Not automatically. UAE civil and commercial judgments carry no automatic reciprocal enforcement in the UK, so creditors generally need to bring a fresh UK action on the underlying debt or pursue recognition under common-law principles, and our guide to enforcing a foreign judgment in the UK sets out the practical steps.
How long can you legally be chased for a debt in the UAE?
Limitation periods run from the date the debt arose, so timing is critical and acting late can close off remedies you would otherwise have. The exact period depends on the type of debt and the contract terms involved, which is why early legal advice on your specific case matters.
Can you be stopped at the airport for debt in the UAE?
Yes, UAE legislation allows courts to impose travel bans as a precautionary measure where there is a real risk the debtor will evade payment or move assets out of reach, as set out in UAE legislation governing interim measures. These bans are usually sought alongside or ahead of other enforcement steps rather than as a stand-alone remedy.
Can overseas debt be enforced in the UK?
It depends on where the debtor’s assets or connections sit. UK guidance confirms that overseas debt recovery works best when the debtor owns UK property, works for a UK-established employer, or holds other enforceable UK assets, and without that link, UK enforcement is often impractical.
Sources
- Debt recovery for businesses in the UAE: court process and legal options — Chambers
- A strategic guide for creditors in the UAE — Clyde & Co (2026)
- Debt recovery & legal proceedings in the UAE — Inlex Partners
- UAE legislation (Civil/Bankruptcy provisions) — official texts
- Gov